 Contact Us
86,896 approved. 15,584 paid out. Those are the latest official numbers for the Wazir-e-Azam Apna Ghar Program. At the Access to Finance Steering Committee meeting on 28 October 2026, the Finance Ministry reported:
Measure | Figure |
Applications approved | 86,896 |
Financing approved | Rs 511 billion |
Loans disbursed | 15,584 |
Amount disbursed | about Rs 91 billion |
So only about 1 in 6 approved applicants had received money by then. Approval is a big step, but it is not the finish line. Property papers, valuations, and bank checks still have to clear before the loan is paid.
Owning a home in Pakistan is hard. Prices are high, and normal bank loans cost a lot. Many families rent for years because they cannot save a full payment. The Apna Ghar Program was built to close part of that gap for first-time buyers. It is the federal government's housing finance scheme, run through banks under the State Bank of Pakistan (SBP). It gives first-time homebuyers long-term loans at a low fixed markup, so a monthly instalment can look more like rent than a burden.
This guide shows you how it works, who qualifies, and how to apply without slowing yourself down.
What Is the Wazir-e-Azam Apna Ghar Program?
The Wazir-e-Azam Apna Ghar Program is a government-backed housing loan scheme for Pakistanis who do not yet own a home. It is also called "Ghar Ho Tu Apna." It offers financing of up to Rs 10 million at a fixed 5% markup for the first 10 years. Applications are made online and processed by participating banks.
The main goal is simple: help more families own a home. Normal home loans are priced at market rates, which are often too high for middle-class and lower-income families. A fixed 5% rate for 10 years makes instalments smaller and easier to plan.
Overview of the Government's Affordable Housing Finance Initiative
Prime Minister Shehbaz Sharif launched the program on 30 April 2026. At launch, the government set clear goals:
Rs 321 billion in financing in the first year
50,000 houses in the first phase
500,000 houses over four years
Coverage in all four provinces, Gilgit-Baltistan, and Azad Kashmir
The State Bank of Pakistan oversees how banks run the scheme. Commercial banks, Islamic banks, microfinance banks, and House Building Finance Company (HBFC) all take part.
How Does the Program Support First-Time Homebuyers?
For a first-time buyer, the two biggest hurdles are the down payment and the monthly cost. The program helps with both. You only need to put in at least 10% of the property's cost. The bank covers up to 90%. The scheme also aims to boost construction. More homes being bought and built means more work for builders, labour, and construction material suppliers.
The low markup then keeps instalments steady for 10 years. Here is what that looks like, according to Daily Pakistan:
Loan amount | Estimated monthly instalment (20-year term) |
Rs 2.5 million | Rs 16,499 |
Rs 5 million | Rs 32,997 |
Rs 7.5 million | Rs 49,497 |
Rs 10 million | Rs 65,996 |
These figures cover the 5% period. After year 10, the rate moves to market pricing, so the instalment can change.
Main Features of the Apna Ghar Program
These are the terms most buyers ask about first.
Housing Finance Options Available Under the Scheme
The program offers four loan slabs. You choose the one that fits your budget and property:
Up to Rs 2.5 million
Up to Rs 5 million
Up to Rs 7.5 million
Up to Rs 10 million
The financing is available in both conventional and Islamic modes, through commercial banks, Islamic banks, microfinance banks, and HBFCs. A list of participating banks is published on the official portal at apnaghar.gov.pk.
Financing Amount and Applicable Markup Structure
The most you can borrow is Rs 10 million. Markup is fixed at 5% for the first 10 years. After that, it moves to a market-based rate set by your bank.
Repayment Period and Financing Terms
You can repay over up to 20 years. A longer term means smaller instalments, but you pay markup for longer. The fixed 5% only covers the first half of a 20-year loan, so plan for a possible rise later.
Applicant Contribution and Bank Financing
You must pay at least 10% of the property cost yourself. The bank can finance up to 90%. On a Rs 5 million home, that means at least Rs 500,000 from you and up to Rs 4.5 million from the bank.
Banks also check that you can afford the loan.
Processing Charges and Early Repayment Conditions
Good news here. The SBP has told banks not to charge any processing fee. You can also repay early without a prepayment penalty. That lets you clear the loan faster if your income grows.
Who Is Eligible for the Wazir-e-Azam Apna Ghar Program?
Attractive terms only help if you qualify. The rules are fairly broad, but a few of them are strict. Check each one before you start your application.
Basic Eligibility Requirements for Pakistani Citizens
According to Aaj News guide to the scheme, you should meet these basic conditions:
Pakistani citizen with a valid CNIC
Aged 20 to 65 years
Minimum monthly income of Rs 40,000
Salaried: at least 6 months in your current job
Business owner: at least 2 years of business experience
Pass the bank's income and credit checks
Eligibility Requirements for First-Time Homebuyers
This is the most important rule. The scheme is only for first-time homebuyers. You must not own a residential property in your name.
Eligibility Requirements for Overseas Pakistanis
Yes. An SBP official confirmed in July 2026 that overseas Pakistanis are eligible. You will still need to meet the first-time buyer rule and the bank's income checks. Ask your bank which documents it accepts for income earned abroad.
Eligibility Requirements for Salaried Employees
Yes. Salaried people with documented income can apply. You will need at least six months in your current job. The bank will use your salary slips and bank statements to check how much you can repay each month.
Eligibility Requirements for Self-Employed and Business Owners
Yes. Business owners need at least two years of business experience. If your income is informal, you can apply jointly with up to three other people, such as earning family members, to meet the repayment test.
Types of Properties Covered Under the Apna Ghar Scheme
The scheme covers three main uses, all within clear size limits.
Buying a House or Flat: You can use the loan to buy a ready-built house or an apartment. The house must be within the size limit, and the flat must be up to 1,500 square feet.
Constructing a House on an Already-Owned Plot: Yes, the scheme covers this. A plot of up to 10 marla is eligible property for construction. Banks usually release construction finance in stages, as the work progresses.
Purchasing a Plot and Constructing a House: The sources do not clearly state whether the same loan can also pay for buying the plot. If you plan to buy a plot and build, ask your bank to confirm in writing before you commit.
Property Size and Covered Area Requirements
Property type | Maximum size |
House (bought or built) | Up to 10 marla |
Plot for construction | Up to 10 marla |
Apartment or flat | Up to 1,500 sq ft |
How to Apply for the Wazir-e-Azam Apna Ghar Program Online
You know you qualify and what you can buy. Now for the application itself. It is fully online, and there is no paper form to download. The steps below follow a step-by-step guide.
Step 1: Visit the Official Apna Ghar Program Portal
Go to the official portal at apnaghar.gov.pk. Type the address yourself. Avoid links from social media or unknown websites, because fake sites can steal your details.
Step 2: Create Your Applicant Account
Click "Create Account." Register using your CNIC number and personal details. Use a mobile number and email address you check often, since updates may come there.
Step 3: Log In and Complete the Application Form
Log in with your new account. On the dashboard, click "Apply for Loan" to open the online form.
Step 4: Enter Personal and Financial Information
Fill in your name, CNIC, contact details, monthly income, and how much financing you need. Make sure every entry matches your CNIC and income papers exactly.
Step 5: Provide Employment and Property Details
Add details of your job or business. Then describe the property you want to buy or build. You will also choose your preferred participating bank here.
Step 6: Upload the Required Documents
Upload clear scans or photos of your documents when asked. Blurry or cut-off files are a common reason for delays.
Step 7: Review and Submit Your Application
Read every field one more time. Fix any typing mistakes. Then submit the application electronically.
Step 8: Follow Up With the Participating Bank
After you submit, your chosen bank takes over. It checks your identity, income, repayment capacity, credit history, and property papers. The SBP requires banks to give a credit decision within 15 working days of receiving a complete application.
The portal steps take one sitting. The bank stages take longer because property papers and valuation must clear before any money is paid.
Related: https://gharhub.com/house-construction-process-pakistan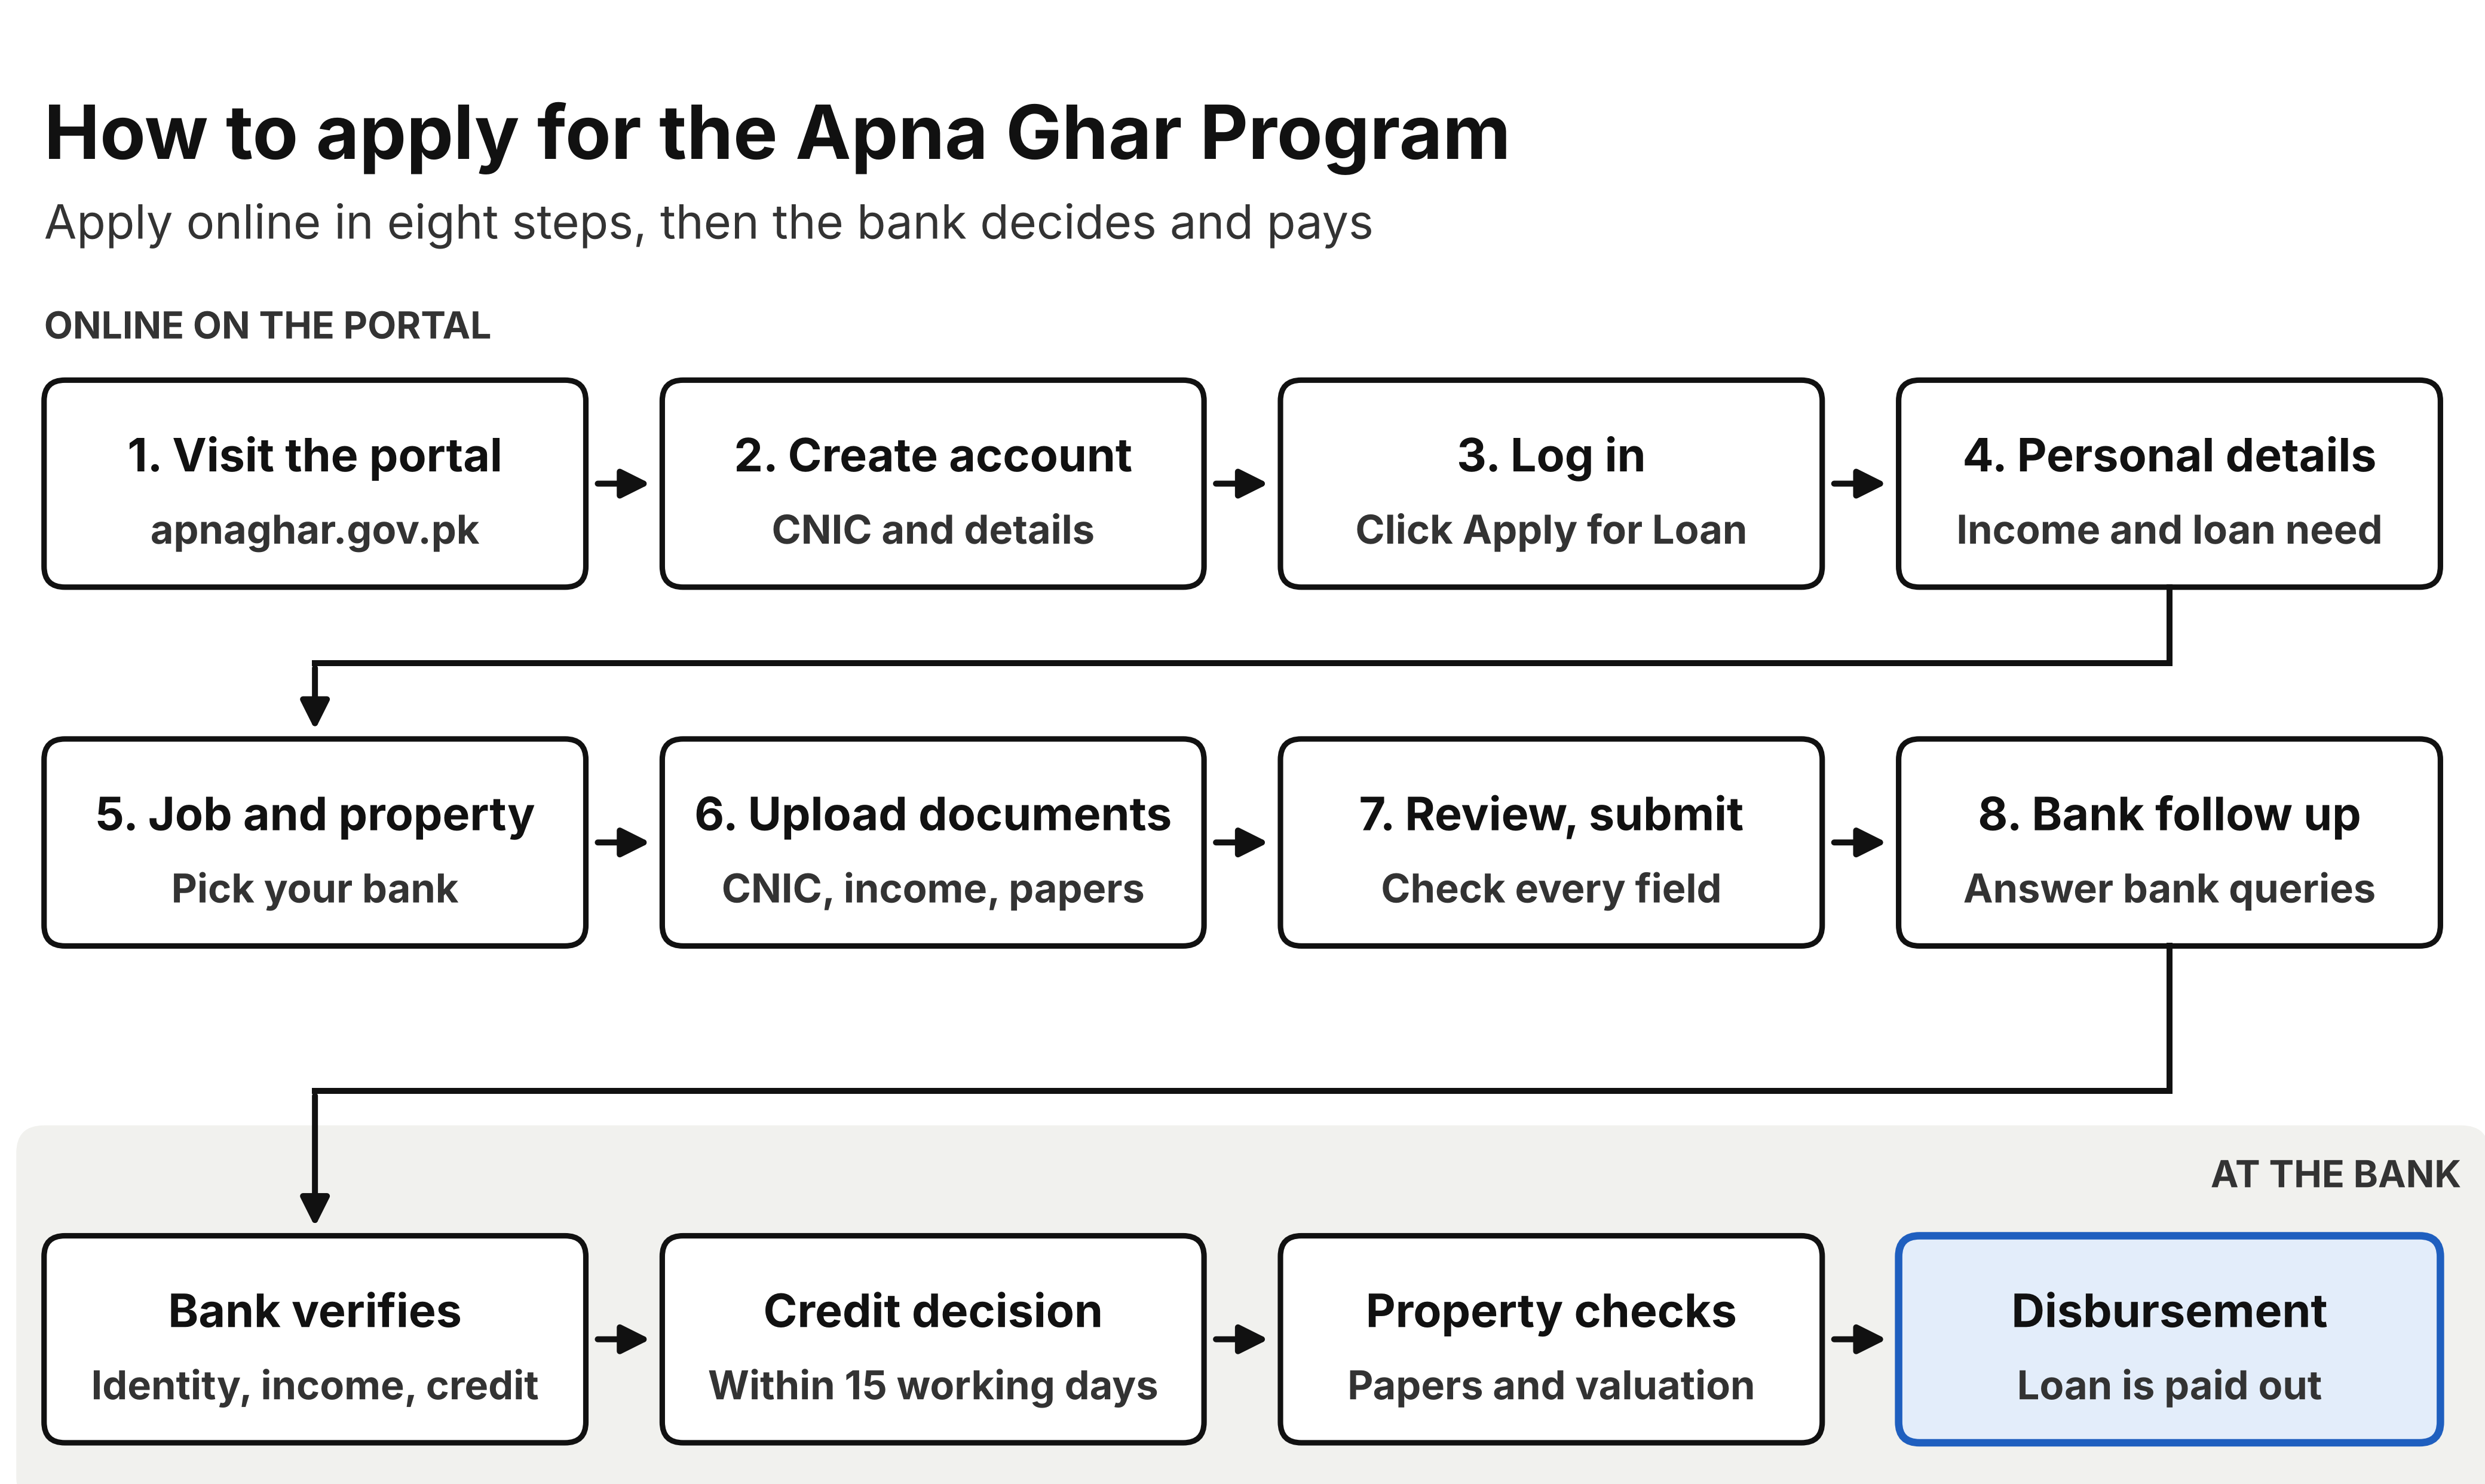
What Documents Are Required for the Apna Ghar Program?
Having the right papers ready before you start saves days. The core list includes your CNIC, recent photographs, proof of income, bank statements, job or business documents, and property papers. Each bank may ask for more, so check its list too.
Documents Required for Salaried Applicants
If you earn a salary, your bank will mainly look at how steady your pay is. Keep these ready:
Valid CNIC
Recent passport-size photographs
Latest salary slips
Bank statement showing your salary credits
Employment certificate from your employer
Property documents, if you already have a property in mind
Documents Required for Business Owners
Business owners must show at least two years of business experience. Banks usually want proof that the business is real and earning. Common papers include your CNIC, business bank statements, business registration or proof of business, and tax returns if you file them.
Documents Required for Informal Income Applicants
The SBP allows people without formal pay slips to apply. Without pay slips, your bank statements become your main proof of income. Keep your earnings flowing through one bank account where possible. Applying jointly with an earning family member can also help you pass the repayment check.
Documents Required for Co-Applicants
You can apply with up to three other people, such as close family members. Each co-applicant will normally need their own CNIC, photographs, and proof of income. Banks may also ask for proof of your relationship. Every co-applicant's income and credit history will be checked too.
People Also Search For: https://gharhub.com/building-house-for-50-lakh-2026-guide-gharhub
Wazir-e-Azam Apna Ghar Program vs Other Housing Finance Options
With your papers sorted, it is worth asking: is this the best loan for you? Comparing it with other options shows where it stands out and where it does not.
Government-Subsidized Housing Finance vs Conventional Home Loans
A normal bank home loan is priced on KIBOR, the rate banks lend to each other, plus the bank's own margin. That rate moves up and down with the economy. The Apna Ghar Program fixes your markup at 5% for 10 years, so your instalment stays steady and easy to plan. The trade-off is limits. Normal loans can fund bigger homes, while Apna Ghar caps the loan at Rs 10 million and the house at 10 Marla.
Provinces also run their own schemes, such as Punjab's Apni Chhat Apna Ghar. Their rules, amounts, and eligibility are different, so read each one separately.
Key Differences in Financing and Repayment
Here is the short version of how Apna Ghar compares with a conventional home loan:
Feature | Apna Ghar Program | Conventional home loan |
Markup | Fixed 5% for 10 years, then market rate | Market rate (KIBOR plus margin) |
Maximum loan | Rs 10 million | Set by the bank |
Property size limit | 10 marla house, 1,500 sq ft flat | Usually none |
Buyer type | First-time buyers only | Any eligible borrower |
Processing fee | None | Set by the bank |
Prepayment penalty | None | Set by the bank |
What Are the Common Reasons for Application Rejection?
Remember the gap from the start of this guide: tens of thousands of approvals, but far fewer payouts. Not every application gets through, and some get stuck. Knowing why helps you avoid the same traps.
Incomplete or Incorrect Application Details: A wrong CNIC digit, a name spelled differently from your CNIC, or an empty field can stop your file
Missing or Invalid Documents: Expired CNICs, blurry scans, and missing pages are common problems.
Income and Repayment Capacity Issues: Banks must check that you can afford the instalments. Your total loan payments cannot go over 65% of your net disposable income. If you already pay a car loan or credit card, there is less room for a home loan.
Property Documentation Problems: Property checks can take time. The property's title must be clear and its papers complete. The house or flat must also stay within the size limits.
How to Avoid Common Application Mistakes
A little preparation goes a long way. Run through this list before you click submit:
Make sure your name and CNIC match on every document.
Scan each document clearly, with all pages included.
Work out your monthly instalment and compare it with your income.
Pay down small loans if your debt burden is close to the limit.
Choose a property with clear, complete papers within the size limit.
Reply to your bank's questions quickly.
Final Takeaway
The Wazir-e-Azam Apna Ghar Program gives first-time buyers a real path to owning a home. You can borrow up to Rs 10 million at a fixed 5% markup for 10 years, repay over up to 20 years, and put in as little as 10% yourself. There is no processing fee and no penalty for paying early.
Clear papers, honest details, and a property with a clean title make the difference between an approved file and money in your account. Before you apply, confirm the current terms on apnaghar.gov.pk and with your chosen bank. Apply only through the official portal or a participating bank, never through agents who ask for fees.
And once your financing comes through, the next big job begins: building and finishing your home. The quality of the materials you choose will decide how well that home lasts.
Frequently Asked Questions About the Wazir-e-Azam Apna Ghar Program
What Is the Wazir-e-Azam Apna Ghar Program?
It is the federal government's housing finance scheme for first-time homebuyers, also called "Ghar Ho Tu Apna." It offers loans of up to Rs 10 million at a fixed 5% markup for the first 10 years, with repayment over up to 20 years.
Is the Apna Ghar Program Currently Accepting Applications?
The latest official update, on 28 October 2026, showed the program active, with 86,896 applications approved and 15,584 loans disbursed. Applications are made online at apnaghar.gov.pk. Check the portal for the current status before you apply.
Who Can Apply for the Apna Ghar Scheme?
Pakistani citizens with a valid CNIC who do not own a home can apply. Applicants should be 20 to 65 years old with a monthly income of at least Rs 40,000. They must also pass the bank's income and credit checks.
Can Overseas Pakistanis Apply for the Program?
Yes, overseas Pakistanis are eligible. They must still be first-time homebuyers and meet the bank's income requirements.
Can I Apply if I Already Own a Plot?
Yes, if you do not own a house. The scheme covers building a house on a plot of up to 10 Marla. Owning a residential property, however, makes you ineligible.
Can I Use the Scheme to Construct a House?
Yes. You can use the financing to build a house of up to 10 Marla on your plot. Banks usually release construction finance in stages as the work progresses.
How Can I Check My Application Status?
Log in to your account on apnaghar.gov.pk to see your application. You can also contact your chosen bank directly, since it handles the review and decision.
How Long Does Application Approval Take?
Banks will give a credit decision within 15 working days of receiving a complete application. Property checks and disbursement can take longer.
Can I Apply Through a Bank?
Yes. Besides the online portal, participating bank branches have counters to help applicants. The list of participating banks is on the official portal.
Does Application Submission Guarantee Approval?
No. Each bank checks your eligibility, income, credit history, and property papers. Approval also does not guarantee immediate payment.